

Advertisements
Do you want to save real money on groceries, fashion, and home items? The best option is to use the Woolworths credit card rewards South Africa program. It turns your routine expenses into instant checkout discounts and cashback balance directly in your digital account.
Today, you will learn in depth how Woolworths credit card rewards South Africa works. You will understand the return percentages offered, operational fees, and interest rates for each card. Minimum salary requirements for approval are also covered.
If you want to find the ideal card to boost your budget and avoid unnecessary fees, keep reading to discover if applying for your Woolworths credit card rewards South Africa is truly worth it.
Detailed Analysis of Woolworths Credit Card Rewards South Africa
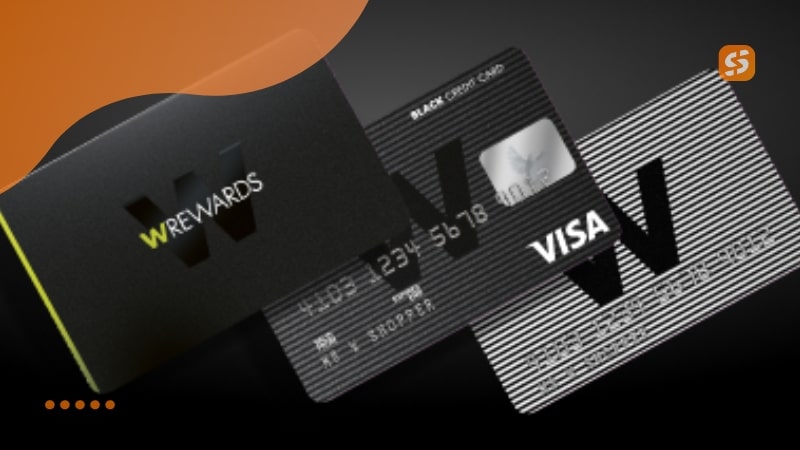
The card line is structured in three tiers with increasing income requirements, balancing fixed monthly costs with commercial perks calculated for different spending levels.
1. Woolworths Silver Credit Card
The Silver-tier card serves as the entry point to the institution’s credit portfolio. It is aimed at young professionals starting their careers, students, and entry-level workers who need to build a formal banking history.
To have your application evaluated, the net monthly income requirement is very accessible, set at just 2,000 Rands.
In return, the product grants a 1% reward on purchases made at Woolworths stores and 0.5% on general expenses paid at any merchant accepted by the Visa network.
Another practical feature is the ability to issue up to eight additional cards without extra maintenance fee charges. This allows you to centralize dependents’ spending and accelerate reward earnings under a single shared credit ceiling.
However, the economic viability of this option requires extreme care with its operational fee schedule.
In fact, Silver card account maintenance incurs a monthly fee of up to 62 Rands, along with a credit facility fee of 30 Rands for active contracts. An initial initiation fee of up to 199 Rands is also charged on the very first financial statement.
Since annual interest rates for revolving balances hover around 21% to 22%, any unpaid balance or payment below the statement total immediately cancels out the benefit gained from the 1% return.
This card is ideal for cardholders who need a credit line for everyday purchases and commit to paying off their entire statement balance each billing cycle.
2. Woolworths Gold Credit Card
The Gold tier serves middle-class families and individuals with stable incomes who visit the brand’s supermarkets and fashion departments on a weekly basis.
To qualify for this intermediate tier, the institution requires proof of monthly income between 3,000 and 10,000 Rands. This depends on credit bureau ratings and the applicant’s debt capacity.
The reward percentage doubles compared to the basic tier, generating up to 2% back on spending at Woolworths and 0.75% on transactions processed externally on the Visa network.
An attractive feature of this card is the automatic application of an extra 5% discount at checkout on items already on sale through the loyalty program. This totals instant savings of up to 15%. Additionally, emergency medical and legal assistance coverage is valid for up to 90 days on international trips.
However, the cost to maintain a Gold card account rises up to 70 Rands per month, while retaining the fixed 30 Rands credit facility fee and an initiation fee of up to 199 Rands.
The critical point of this tier lies in the minimum purchase volume required to offset expenses. If a consumer makes sporadic purchases or carries balances subject to annual interest of up to 22%, the 2% return becomes financially useless.
In fact, Gold cardholders need to concentrate a substantial portion of their household budget with the retailer. This ensures that bonuses and discounts comfortably exceed monthly operating costs, which reach nearly 100 Rands each month.
3. Woolworths Black Credit Card
The Black card occupies the top of WFS’s hierarchy and was designed for executives, independent professionals. And high-net-worth consumers who concentrate most of their lifestyle and shopping with the brand.
Be aware that admission criteria reflect this premium profile, requiring proven earnings of at least 41,666 Rands per month.
In return, cardholders enjoy a 3% return on all purchases made in physical stores. And online at Woolworths and 1% at external merchants, a perk that even extends to fuel fill-ups at gas stations.
By meeting MyDifference PLUS goals, cashback can reach up to 10%. The package includes clear value perks such as two complimentary coffees or teas per month at Woolworths Cafés and free home delivery on all purchases made through the app or website. Purchases are also covered for up to 24 months, with theft or accidental damage protection for 90 days.
Even though free delivery and café perks easily offset this fee for frequent shoppers. Interest rates of up to 22% per year severely penalize anyone carrying debt on this card.
It is tailor-made for financially disciplined customers who spend substantial amounts and use the card strictly as a convenient payment and rewards collection method, paying off 100% of their balance each month.
If you’d like to compare this option with others, start with Nedbank platinum credit card benefits. That way, you can be sure you’re getting the best deal.
What Do Customer Reviews Say About Woolworths Credit Card Rewards South Africa?
Before submitting an application, it pays to review the company’s operational performance regarding daily demand. And unexpected issues reported by other cardholders.
On the South African consumer review portal HelloPeter, Woolworths’ reputation across financial and retail services faces low ratings. It maintains an average score of just 1.4 out of 5 stars and a TrustIndex score fixed at a modest 2 out of 10 points.
The Net Promoter Score also lands in negative territory, highlighting recurring dissatisfaction in specific customer service areas.
The primary complaints center on delays in producing and delivering physical cards.
Numerous customers report that even after receiving online approval, they had to visit physical store counters repeatedly. This was due to technical glitches with card embossing machines or synchronization failures with the central system.
These experiences underscore the importance of keeping payment receipts and tracking credit limits through official digital channels whenever possible.
Conclusion
The conclusion regarding the program’s value rests entirely on the cardholder’s spending habits and budget management discipline.
Consider shoppers who routinely buy groceries at the brand’s supermarkets and purchase items from their apparel line. If they strictly pay off their full statement balance every billing cycle, these cards prove to be highly effective tools.
Under controlled spending habits, combining discounts of up to 15%, earning cashback through MyDifference PLUS, and enjoying perks like free delivery and drinks brings great value. These benefits comfortably outweigh monthly service fees.
On the other hand, if you frequently rely on revolving credit, carry monthly balances. Or shop at the store only occasionally. Administrative fees combined with interest rates of 21% to 22% will easily wipe out any earned rewards.