

Advertisements
Finding affordable credit without compromising the household budget can be exhausting. Especially when facing abusive revolving interest charges. When looking for information about Tesco Bank loans UK, many UK consumers fear facing excessive bureaucracy or hidden fees that destabilize their finances.
In this guide, we present everything for those seeking predictability through Tesco Bank loans UK, detailing amounts from £3,000 to £35,000, rates starting from 6.2% APR, and clear borrowing rules. We explain all the modalities available in the banking catalog to facilitate your comparative analysis.
Quickly understanding how Tesco Bank loans UK work in practice allows you to save substantial amounts over the months. Follow the information below and identify the ideal credit option for your profile.
What Tesco Bank Loans UK Are and How They Work
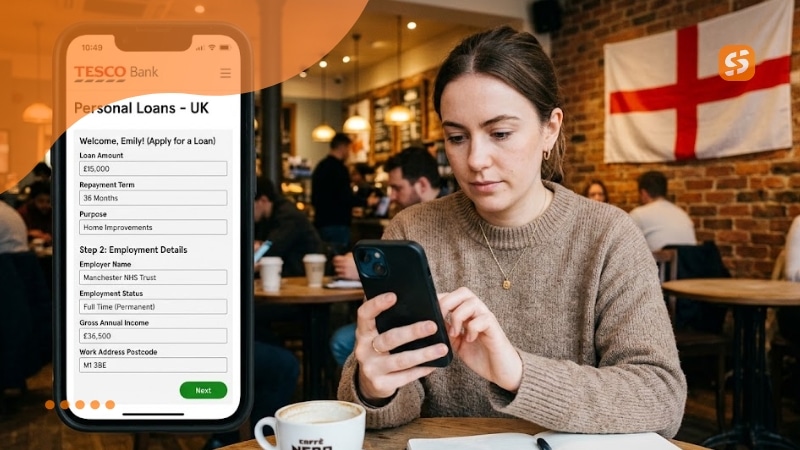
The loans offered by Tesco Bank are unsecured personal loan agreements. They are operated in institutional partnership with Barclays Bank UK PLC’s structure.
This means that releasing the funds does not require assets like real estate or vehicles to be pledged as direct collateral for the operation.
The granted capital typically ranges between minimum amounts of £3,000 and regulatory caps of £35,000, offering flexible repayment terms ranging from 12 to 120 months.
The entire cost of borrowing is summarized in the Representative APR, the official UK standard benchmark supervised by the Financial Conduct Authority (FCA).
Monthly installments remain strictly fixed from the first to the final due date via automated Direct Debit.
At the start of the schedule, the proportion of interest on the outstanding balance is high, but subsequent amortizations gradually reduce the principal balance until its full settlement.
The institution also offers protective operational features, such as the option to request an initial payment break of two months.
During this period, although installment collection is deferred, interest continues to accrue on the open balance, proportionally extending the duration of the agreed obligation.
Understand All Tesco Bank Credit Lines Now
The institution’s credit portfolio is strategically organized into categories designed for specific budgetary purposes, ensuring predictability and suitability for multiple stages of the borrower’s financial life.
1. Car Loan (Tesco Bank loans UK)
Car loans provide amounts between £3,000 and £35,000, ensuring full ownership of the vehicle immediately upon purchase.
Unlike contractual models such as Hire Purchase or Personal Contract Purchase, this option eliminates annual mileage restrictions or clauses reserving ownership rights for the bank.
Furthermore, terms range from 1 to 5 years for amounts under £15,000, reaching up to 8 to 10 years for larger loan tiers.
Tesco Clubcard holders can access attractive fixed rates starting from 6.2% APR for amounts between £7,500 and £25,000, while regular customers register average benchmark rates around 6.6% APR.
As a point of caution, applicants with a modest credit score may receive offers with interest rates reaching higher levels up to 34.5% APR.
2. Home Improvement Loan (Tesco Bank loans UK)
Targeted for interior renovations, room additions, roof replacements, or kitchen modernizations, this financing covers amounts from £3,000 to £35,000.
First, the competitive advantage of this line is the ability to spread payments over terms up to 10 years (120 months), even for amounts below £15,000—a feature often restricted in other options.
Rates maintain promotional values starting from 6.2% APR for members of the store loyalty program.
The drawback lies in the overall total cost, as very extended term plans result in continuous interest accumulation that increases the total cost of the project over the long term.
3. Debt Consolidation Loan
Designed with the goal of restructuring household finances.
This option combines credit card balances, overdraft limits. Expensive store credits into a single monthly payment between £3,000 and £35,000.
The lender caps repayment terms at 5 years for loans under £15,000 and extends options up to 7 years for borrowing up to £35,000.
As a rule, rates start at 6.2% APR for eligible Clubcard customers, providing immediate relief to monthly cash flow.
The main drawback focuses on access strictness, requiring a restrictive minimum age of 22 and solid proof of budget stability.
4. Personal Expenses and Events Loan
Ideal for specific life events such as weddings, family celebrations, travel costs, or urgent unexpected expenses. This solution offers standard amounts from £3,000 to £25,000 with repayment terms from 1 to 5 years.
Consider that the holder enjoys fast liquidity and has the freedom to make voluntary partial overpayments at any time without contractual penalty fees.
Furthermore, rates for qualified profiles start at low levels. Although applicants categorized into higher risk tiers may face significantly high APRs.
In addition, repaying the loan agreement in full early incurs a statutory retention of up to two months’ interest charges by the institution.
5. Joint Loan (Tesco Bank loans UK)
A joint loan allows two individuals, such as spouses or cohabiting family members. To combine resources to apply for loans between £7,500 and £35,000 with repayment horizons of up to 10 years.
In this option, the technical advantage of the operation lies in combining declared income. Boosting approval chances with competitive rates starting from 6.2% APR.
Conversely, the legal structure imposes full joint and several liability, holding both parties responsible for repayment if one party defaults.
The lender requires you to set up the monthly Direct Debit using the primary applicant’s bank account.
This product suits couples and business partners planning shared major investments with fully aligned finances.
Learn How to Apply for Tesco Bank Loans UK
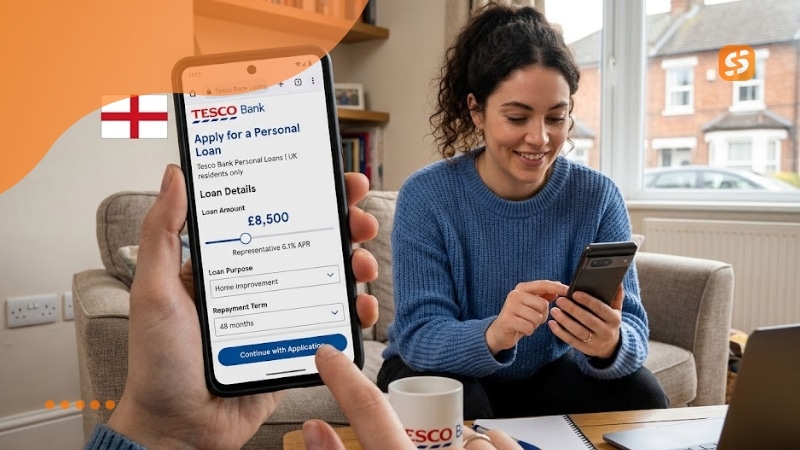
The application submission process was digitally designed by Tesco Bank to align convenience with compliance regarding UK responsible lending rules.
The first step involves using the online eligibility checker. The tool runs a soft credit check, evaluating profile information and estimating approval likelihood without impacting the consumer’s credit score.
Upon receiving a positive signal, the applicant inputs loan preferences regarding amount, repayment term. Tesco Clubcard details, activating promotional discounted interest rate tables.
Next, the applicant completes registration details providing three years of fixed UK residency address history and stable income documentation.
The formal application authorizes a binding hard credit check with regulated credit reference agencies such as Experian and Equifax.
Once the lender approves your credit, you sign the digital contract online to receive your funds via Faster Payments within 24 to 48 hours.
Conclusion
Tesco Bank personal loans offer a structured and secure financial solution. Guaranteeing fixed monthly installments without requiring property or assets as collateral.
Consider that the portfolio caters to everything from minor home renovations to vehicle purchases and strategic debt consolidations.
To take advantage of the most favorable terms and benefit from Clubcard discounted rates, carefully plan your monthly household budget.
Before finalizing any credit agreement, critically evaluating the UK financial market is essential to saving significant amounts over the long term.
To explore other solid alternatives with strong banking reputations. Check out our analysis of Santander loans UK options. Discover which institution offers the most advantageous conditions for your financial situation.