

Advertisements
Finding an affordable loan without paying excessive interest becomes challenging when researching Barclays personal loan rates. Choosing the wrong term or amount increases your monthly repayments. This strains your household budget.
To avoid costly mistakes, we analyzed current Barclays personal loan rates. We compiled cost breakdown tables, eligibility criteria, and direct market comparisons into an accessible, practical guide.
Before submitting a formal application to the bank, read on. Discover how to secure the most competitive Barclays personal loan rates and save hundreds of pounds across your agreement.
What Are Barclays Personal Loan Rates and How Do They Work?
Barclays markets its unsecured personal lending under the official brand name Barclayloan.
Consequently, you do not need to pledge personal assets to secure financing. Neither your home nor your vehicle serves as collateral in the contract.
The primary benefit of this financing structure is total payment predictability. In the first place, the agreement applies fixed interest rates exclusively.
As a result, your monthly instalment remains identical from the initial payment to the final month. Unplanned rate adjustments do not occur during the term.
Furthermore, advertised loan costs comply with standard Financial Conduct Authority (FCA) regulatory frameworks.
Therefore, promotional material always displays a Representative APR.
Representative APR or Personalised Rates?
FCA regulations require lenders to grant the advertised rate to at least 51% of approved applicants.
In other words, over half of successful borrowers secure the lowest headline rate promoted by the bank.
On the other hand, the remaining 49% receive a tailored, higher interest rate.
In practice, the lender determines this individual quote by evaluating each applicant’s credit risk profile. Several objective metrics shape your final borrowing cost:
- Your credit score across major UK credit reference agencies.
- Your payment history on existing utilities, loans, and credit cards.
- The exact amount of capital requested in your application.
- The total repayment term selected for the loan.
- Your verified monthly income and professional employment stability.
Barclays Loan Rates Breakdown by Tier and Product
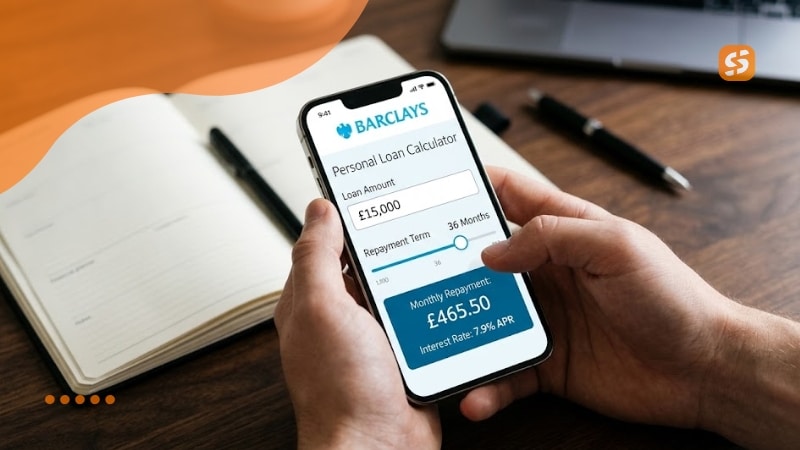
Borrowing costs fluctuate significantly depending on the amount requested. As a general rule in the UK credit market, higher loan amounts carry noticeably lower interest rates than smaller sums.
In practice, the bank’s most competitive pricing applies to amounts between £7,500 and £15,000.
This threshold suits most borrowers seeking home improvements, vehicle purchases, or debt consolidation.
| Loan Product | Borrowing Range | Repayment Terms | Representative APR | Total Cost (£10,000 over 60m) | Estimated Monthly Payment |
| Barclayloan Standard | £1,000 to £50,000 | 24 to 60 months | 7.05% APR | £11,833.20 | £197.22 |
| Premier Barclayloan | £1,000 to £50,000 | 24 to 60 months | 6.65% APR | £11,727.00 | £195.45 |
| Greener Home Loan | £7,500 to £15,000 | 24 to 60 months | 7.05% APR | £11,833.20 (with cashback) | £197.22 |
Standard current account holders borrowing between £7,500 and £15,000 typically pay 7.05% Representative APR.
Additionally, requesting amounts between £15,100 and £20,000 raises the cost slightly to 7.10% APR.
Conversely, qualifying Premier Banking customers receive discounted pricing terms. The bank lowers their annual borrowing cost to 6.65% Representative APR.
As a result, both monthly payments and total financing charges drop visibly.
However, qualifying for Premier status requires meeting strict account criteria.
Customers must demonstrate high annual gross income or hold substantial qualifying investments deposited directly with Barclays.
Loan Amounts, Repayment Terms, and Digital Setup
Barclays provides unsecured borrowing starting at £1,000 up to a ceiling of £50,000. However, requests exceeding £25,000 undergo rigorous underwriting reviews. These reviews assess debt-to-income capacity.
Regarding repayment durations, the lender enforces a repayment window of 24 to 60 months. Therefore, borrowers must clear balances within two to five years. This policy differs from competitors that offer extended terms of seven or eight years.
Limiting terms to five years lowers cumulative lifetime interest charges. In contrast, this shorter duration increases monthly instalment commitments.
The application journey is entirely digital:
- Accessible directly through the Barclays mobile banking app.
- Available via online banking on desktop computers.
- Provides same-day fund disbursements for applications completed between 07:00 and 22:30.
Who Is Eligible for a Barclays Personal Loan?
Unlike open-market lenders, Barclays maintains strict entry requirements for unsecured lending. The bank limits direct digital personal loan applications strictly to existing customers.
Without an established banking relationship, the automated platform rejects online submissions. Mandatory eligibility conditions require applicants to:
- Hold an active current account, savings account, mortgage, or Barclaycard credit card.
- Be at least 18 years of age.
- Maintain permanent UK residency backed by verifiable address records.
- Have a clean credit record free of insolvencies, bankruptcies, or County Court Judgments (CCJs) within the past six years.
Additionally, Barclays conducts preliminary soft credit searches during digital eligibility checks. Thus, you can explore personalised rate quotes without harming your credit file.
Permitted and Restricted Uses of Funds
The bank allows personal loan capital across a broad spectrum of everyday personal needs:
- Undertaking residential remodelling and home extensions.
- Purchasing private cars, motorbikes, or domestic vans.
- Consolidating high-interest card balances into one structured payment.
- Covering wedding events, holidays, or private medical expenses.
Conversely, loan terms strictly prohibit funding the following activities:
- Speculative stock market trading or risky financial investments.
- Funding working capital or business operations for private commercial ventures.
- Direct property acquisitions or purchasing timeshare contracts.
- Gambling, casino games, and sports betting activities.
- Settling court fines, legal penalties, or judicial judgment debts.
Extra Costs, Early Repayment, and Price Guarantees
Barclays charges no initial administration fees or arrangement charges. Borrowers avoid hidden upfront setup fees when executing their contracts.
Furthermore, statutory consumer credit regulations grant a 14-day cooling-off cancellation window.
If you return all borrowed capital within seven days of disbursement, Barclays waives all accrued daily interest charges.
UK credit legislation protects your right to repay loan balances early, either partially or fully. However, lenders may levy statutory interest penalties to offset lost returns:
- Remaining term under 12 months: the lender can apply up to 28 days of interest charges on the settled amount.
- Remaining term over 12 months: the maximum charge equals approximately 58 days (around two months) of interest on the repaid balance.
Barclays maintains a unique consumer benefit called the Price Guarantee. Suppose you secure an identical unsecured loan quote at a lower APR from another lender within 30 days of signing. In that case, Barclays matches that lower rate and recalculates your repayments.
To qualify, the rival quote must share matching loan values, identical repayment durations, and unsecured terms.
This protection allows loyal account holders to secure market-leading pricing without switching banks.
Is a Barclays Personal Loan Worth It?
Barclays personal loans provide predictable budgeting through fixed rates and transparent fee-free terms. For existing account holders, near-instant app disbursements deliver significant convenience.
However, Barclays caters strictly to existing customers and caps repayment terms at five years. Moreover, its standard 7.05% Representative APR does not represent the cheapest option in the wider UK market.
Therefore, run preliminary quotes in the Barclays app, evaluate repayment affordability, and compare alternatives across competing lenders before signing your final credit agreement!
When evaluating traditional high street lenders, benchmarking Barclays against comparable banking peers is essential.
To evaluate how a major rival structures pricing, limits, and eligibility, review our comprehensive analysis of NatWest personal loan rates before committing.