

Advertisements
Getting credit in the UK without paying abusive interest takes work. At this moment, the Santander personal loan UK draws attention due to its low rates. However, it holds rarely mentioned rules.
A small change of 1 in the requested amount lowers your interest, while 1 letter in the mail stalls payout. Understanding these details of the Santander personal loan UK avoids delays and protects your credit score.
Want to know how much the bank charges and if it beats competitors? Read to the end and see how the Santander personal loan UK works before applying for yours.
How does the Santander personal loan UK work in practice?
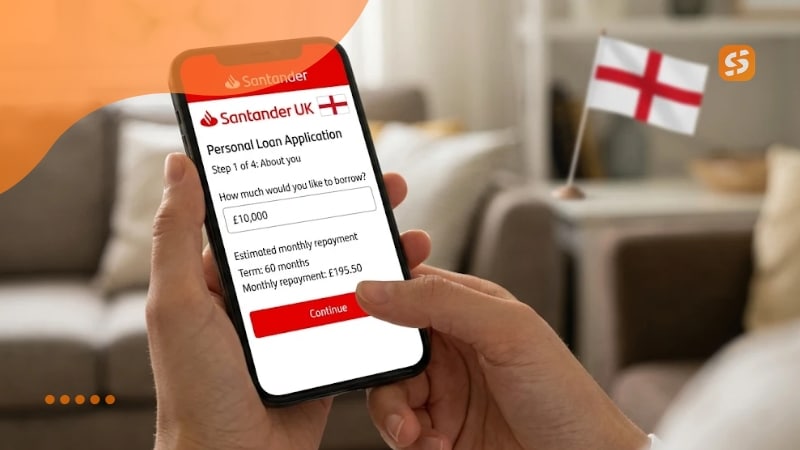
Santander’s personal loan in the UK operates as an unsecured personal line of credit (unsecured personal loan). This means you do not need to provide 1 property or vehicle as collateral to release the money.
The bank updated its rules to serve UK residents with different needs. You can request between £1,000.00 and £35,000.00 to buy 1 car, renovate the house, or combine old debts into 1 single contract.
Repayment terms are fixed and range from 1 to 5 years (between 12 and 60 months, in 6-month increments). Interest rates do not change during the contract. This keeps the monthly payment amount the same until the end, even if the Bank of England changes the base rate.
Applications take place directly on the bank’s website for new or existing customers. Monthly instalments are collected via Direct Debit from the current account registered at the time of signing.
Why asking for a higher amount can lower your interest at Santander UK?
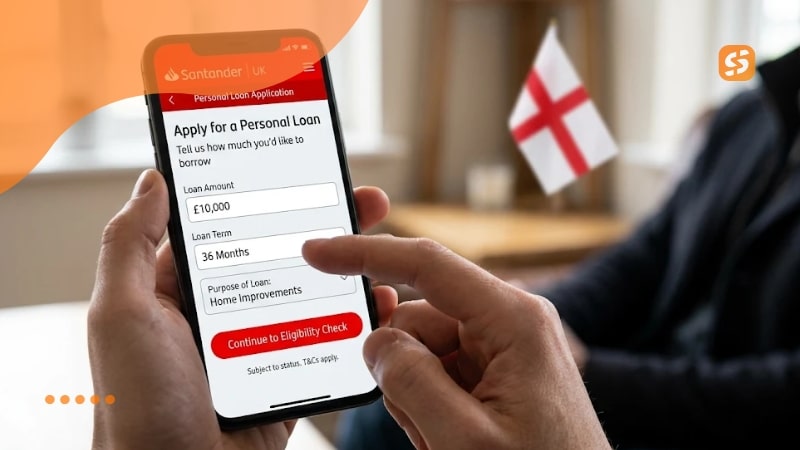
The true cost of a loan in the UK is shown by the APR (Annual Percentage Rate), which reflects the annual rate with interest and charges combined. At Santander UK, this percentage changes according to the requested amount.
Under British law, the rate advertised on the bank’s website is a representative APR. At least 51% of approved customers receive that rate or lower.
The remaining 49% may receive more expensive offers, reaching up to 29.9% APR after risk assessment.
Pay close attention to the tipping points between value tiers (£3,000.00, £5,000.00, and £7,500.00).
Requesting an amount just below these tier thresholds makes the contract more expensive. Requesting £3,000.00 turns out cheaper overall than asking for £2,770.00, because the higher amount falls into a tier with significantly lower interest.
1. From £1,000.00 to £4,999.00 for small projects (Santander personal loan UK)
This tier covers specific expenses or minor household emergencies.
Between £1,000.00 and £2,999.00, Santander charges a 10.6% representative APR. This is a high cost that loses out to digital banks like Zopa (9.9% via John Lewis) or promotional 0% interest credit cards.
The scenario changes between £3,000.00 and £4,999.00, when the rate drops to 8.1% representative APR.
In this range, the loan ranks among the cheapest in the UK across financial comparison sites.
This option works well for anyone seeking smaller amounts with fixed monthly payments. Furthermore, it suits those looking to avoid high interest rates from overdrafts or credit card revolving debt.
2. From £5,000.00 to £25,000.00 for intermediate amounts
This is the bank’s main tier, sought after by those changing cars or consolidating debt.
Between £5,000.00 and £7,499.00, the representative APR stands at 7.5%. From £7,500.00 to £25,000.00, the bank applies its lowest rate of 6.8% representative APR.
Note that the advantage of this tier is charging less than other major traditional British banks for the same amounts. It also reduces final costs by choosing an established institution.
3. From £25,001.00 to £35,000.00 for major goals (Santander personal loan UK)
Santander raised its maximum limit from £25,000.00 to £35,000.00. This way, it caters to larger projects such as structural home renovations. In this upper tier, the representative rate rises only slightly to 6.9% APR and applies to both account holders and non-account holders.
Securing approval in this tier requires proof of higher annual income and maintaining an impeccable credit history. Document verification is usually stricter due to the financial volume involved.
This line serves those with room in their monthly budget who prefer to settle the balance in up to 5 years without involving real estate assets in the operation.
Who can get approved and what does the bank prohibit buying?
Santander UK requires a higher minimum age than competitors like HSBC, Lloyds, and Monzo, which release credit starting at 18. On the other hand, the bank accepts retirees and pensioners without setting a maximum age limit, making it well-rated by this demographic in the UK.
To submit an application with real chances of approval, meet these requirements:
- Age and residency: Be 21 years old or older and permanently reside in the UK.
- Proven income: Be formally employed, self-employed, or receive a pension. You must meet the minimum required annual income (starting from £10,500.00 for smaller amounts and £20,000.00 for contracts above £20,000.00).
- Credit reference history: Maintain a good standing with Experian, Equifax, and TransUnion. There must be no records of bankruptcy, County Court Judgments (CCJs), or Individual Voluntary Arrangements (IVAs) in the last 6 years.
- Active bank account: Hold 1 UK bank account enabled for Direct Debit and disable security locks, such as Experian CreditLock, before filling out the form.
- Joint applications: Each application accepts a maximum of 2 joint holders. They become financially linked on credit bureau records and hold joint liability for the debt.
The bank prohibits purchasing cryptocurrencies with borrowed funds. If Santander identifies indications of loan funds being used for digital currencies, the contract allows immediate cancellation of the agreement and full recall of the debt.
Conclusion
Among British banks, Santander delivers a good balance between low rates and stability. For amounts between £7,500.00 and £25,000.00, its 6.8% APR beats Barclays (7.05%), HSBC (7.1%), and Lloyds Bank (7.4%).
If you are comparing traditional banks in this same intermediate tier.
Check updated details on Natwest loans UK rates. This competitor offers longer repayment terms and deposits funds on the same day for applications approved by 5:45 pm on business days.
In competition with retail networks and digital banks, Santander loses out on the lowest price to M&S Bank (5.9% to 6.1% APR) and Tesco Bank (6.2% with Clubcard).
Apps like Monzo and Zopa deposit funds into the account within minutes and do not charge early repayment penalties.