

Advertisements
The Tesco Bank credit card is one of the most popular options in the UK financial market. It combines ease of approval with the accumulation of everyday rewards.
This range combines no annual fee with the well-known Clubcard program. Thus, it attracts those who want to save on routine purchases. It is also a practical way to manage old debts.
The Tesco Bank Credit Card lineup is currently operated in technical partnership with Barclays Bank. It keeps all original rewards intact. This ensures institutional stability and total security for customers. It does this without losing the essence of the Tesco ecosystem.
Here, you can check how the main zero-interest promotional periods work. Additionally, see the actual rates for each Tesco Bank Credit Card option.
Main Tesco Bank Credit Card Options
Each card model offered by the institution was designed to address a specific consumer need.
Options range from those seeking extended periods to clear accumulated debts. Others serve those who want to spread the cost of new purchases. They also serve those who need to build a good credit score from scratch with UK credit reference agencies.
1. Balance Transfer Credit Card (Tesco Bank credit card)
The Balance Transfer Credit Card represents the option with the longest promotional period in the entire portfolio. It is designed for those who already carry expensive debt on cards issued by other banks.
It offers a promotional period with zero percent interest for up to 36 consecutive months on the balance you transfer from another institution. This allows every pound paid to directly reduce the principal debt. It avoids the erosion of standard interest.
To activate this condition, the bank charges an initial transfer fee of 3.45 percent on the transferred amount. Additionally, the card allows money transfers directly to your current account with zero interest for up to 9 months. This is subject to a 3.99 percent fee.
Suppose the cardholder is unable to pay off the balance within this three-year window. In that case, the annual rate returns to the standard representative rate of 24.9 percent variable per year.
The most critical aspect of this option is that missing any minimum monthly payment results in the immediate cancellation of the entire promotional rate. This exposes the remaining debt to standard interest charges.
For these reasons, this card is widely recommended for those carrying high credit card balances with other providers. It is ideal for anyone needing an extended repayment period with controlled installments to rebalance household finances.
2. Low Fee Balance Transfer Credit Card
Some people want to transfer pre-existing debt without paying a heavy initial fee. They will find a tailored alternative in the Low Fee Balance Transfer card.
First, this option provides up to 15 months of total interest-free status on transferred balances. It applies an administrative fee of just 0.75 percent on the amount brought to the account.
Furthermore, this card offers the convenience of transferring funds to your bank account interest-free for 9 months, paying a 3.99 percent fee. The standard representative APR is maintained at 24.9 percent variable when the temporary benefit expires.
Its drawback is the shorter interest-free period. This requires slightly higher monthly payments to clear the pending total before the end of the 15 months.
3. Balance Transfer and Purchases Credit Card (Tesco Bank credit card)
The Balance Transfer and Purchases card was designed to resolve two distinct financial needs simultaneously. It does not require multiple cards in your wallet.
As a rule, the model offers 21 months without any interest charges. This applies both to new purchases made and to balances transferred from other financial institutions. A 2.95 percent fee is charged on transferred debt within the first 90 days of opening the account.
Its representative rate after the promotional period is 24.9 percent variable. The card also guarantees standard access to direct discounts on highlighted products in Tesco stores.
However, the main disadvantage is the risk of budgetary missteps caused by mixing the repayment of previous debts with new installment plans. This practice can obscure the true total of the monthly bill if payments are not strictly managed.
4. All Round Credit Card (Tesco Bank credit card)
The All Round Credit Card focuses on the convenience of aligning timeframes for different types of everyday financial transactions into a single account package.
It provides 14 consecutive months interest-free on new purchases. It also offers 14 months interest-free for balance transfers from other cards with a 2.49 percent fee. In addition, it guarantees 14 months without interest charges on direct money transfers to the customer’s current account, with a 3.99 percent fee.
The standard contractual rate after the promotional period is 24.9 percent variable per year. Its drawback compared to specialized lines is that the 14-month window is substantially shorter than the 36 months offered by focused debt repayment cards. Therefore, it requires extra discipline to avoid leaving any unpaid balance at the end of the promotion.
5. Everyday Low APR Credit Card
Unlike traditional alternatives based on temporary incentives, the Everyday Low APR skips zero-interest promotional periods altogether. It focuses instead on a consistently low standard rate for everyday use.
Its representative annual percentage rate is fixed at 12.9 percent variable per year. This rate is considerably lower than the average charged by major UK high street banks.
On the other hand, the cardholder does not get promotional windows for balance transfers or interest-free purchases. As a result, standard interest charges apply from the first month if the balance is not paid in full by the due date.
6. Foundation Credit Card (Tesco Bank credit card)
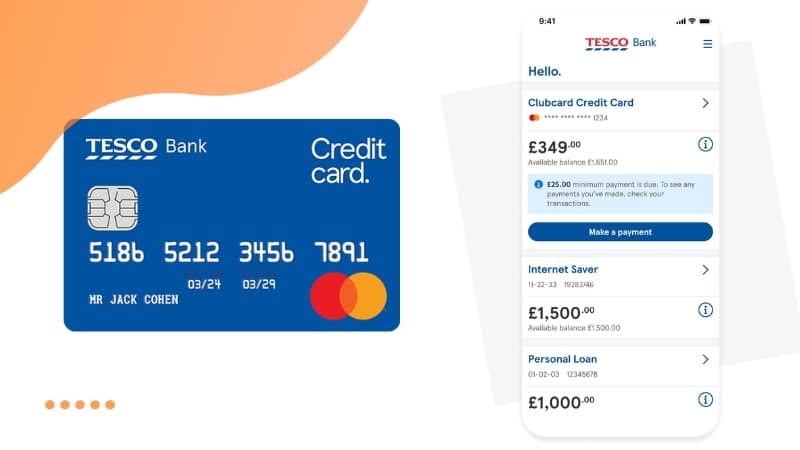
The Tesco Bank Foundation Credit Card operates as a structured tool for financial inclusion and credit rebuilding aimed at higher-risk profiles.
As a rule, it grants controlled initial credit limits, typically set between £200 and £1,500. Minimum monthly payments starting at £25 are required. There is the possibility of gradual limit increases as the customer demonstrates consistent, on-time payments.
Furthermore, the Foundation Credit Card includes free credit monitoring for three years through the Tesco Bank CreditView platform. This offers monthly reports to track your credit score.
The drawback of this option lies in the significant financial cost of its representative 29.9 percent variable APR. This rate is designed to compensate for the risk assumed by the issuer should the user delay payments.
The card is ideal for newcomers to the country without a local credit history and young adults starting out financially. It is also recommended for individuals who faced debt difficulties in the past and need to rebuild credibility with the UK banking system.
Conclusion
The Tesco Bank credit card is an extremely advantageous alternative for anyone looking to eliminate interest on expensive debt. It is also great for saving on family supermarket and fuel purchases.
In addition, the lack of an annual fee and flexible interest-free windows provide excellent financial relief when managed with discipline.
However, to get the maximum benefit, paying installments strictly on time is essential. Moreover, avoid using the card abroad or for cash withdrawals. These options carry high fees.
Try the eligibility checker on Tesco’s website right now to discover your actual chances of approval without affecting your credit score. Choose the ideal version for your financial situation.
Want to see more options? Then check out NatWest credit card rewards now; the bank offers various benefits that make Tesco Bank’s offerings not worth it.