

Advertisements
The TymeBank credit card South Africa promises financial relief and democratization. However, many consumers still face doubts. We will answer them today.
Today, we will look at all the details of the TymeBank Credit Card. We will learn what the real income and documentation requirements were. We will also cover maintenance fees and charges, in addition to all the advantages of this card.
So, want to know everything about the TymeBank credit card South Africa? Understand all the details now. Find out whether this card is right for you or not.
What is TymeBank and How Did Its Credit Card Come About?
Founded in 2019 under the control of African Rainbow Capital (ARC), TymeBank combines 100% digital accounts via an app with physical kiosks. These biometric self-service kiosks are installed in high-traffic retail chains such as Pick n Pay and Boxer.
With free account opening and instant issuance of a Visa debit card, the institution gained millions of account holders.
However, to expand its monetization, offering credit was essential.
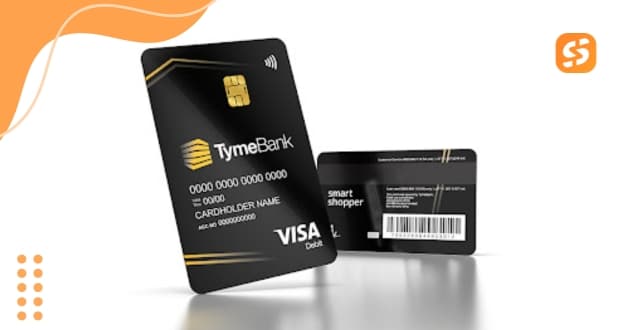
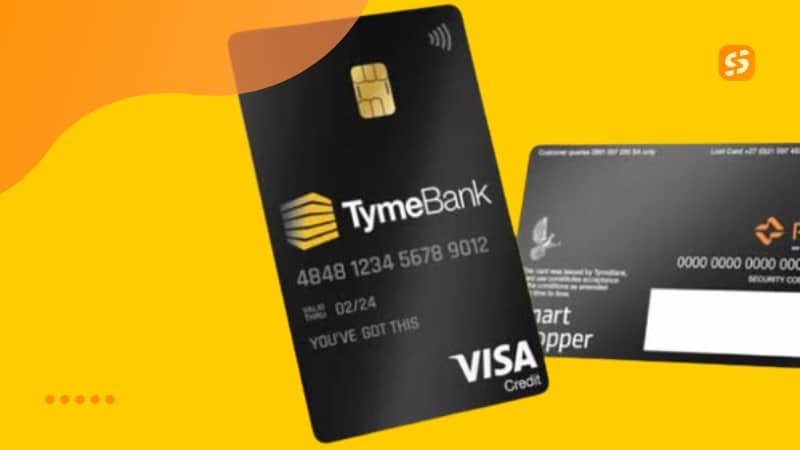
It was in this context that the institution officially launched the TymeBank Credit Card Visa.
The goal was to accelerate credit granting without fully bearing the heavy capital requirements and balance sheet risk regulated by the South African Reserve Bank (SARB).
To achieve this, the bank adopted a white-label partnership model with RCS Cards, a division of BNP Paribas Personal Finance and one of South Africa’s largest consumer credit providers.
Main Costs of the TymeBank Credit Card South Africa
Does the TymeBank credit card South Africa have these costs today?
| Fee Component | Amount / Condition |
| Initiation Fee | R160,00 |
| Monthly Maintenance Fee | R40,00 |
| Interest-Free Period | Up to 55 days |
| Annual Percentage Rate (APR) | From 18% (variable) |
| Available Credit Limit | R1 000 to R50 000 |
| SMS Security Alerts | Free (R0.00) |
| Local In-Store Transactions (POS) | Exempt (R0.00) |
| International Transaction Fee | 2.00% of the amount |
| Additional Cards | Up to 3 cards |
How the Smart Shopper Points Program Works on the TymeBank Credit Card
The credit card’s main commercial differentiator lay in its integration with Smart Shopper, the loyalty program of the Pick n Pay network.
It works like this: the customer accumulated points on all worldwide purchases on the Visa network. However, they received promotional multipliers of up to four times the normal points when using the card directly at the chain’s supermarket stores. This encouraged continuous use for essential household consumption.
In addition, fee waivers for SMS alerts resolved a common complaint among account holders at traditional banks in the region. Such institutions typically charge between 0.40 and 1.35 per notification.
Who Can Apply for the TymeBank Credit Card?
The main draw of TymeBank compared to competitors was the low minimum salary requirement. Check the requirements:
- Minimum Monthly Income: R3 000. Competitors like Capitec and Standard Bank required R5 000 or more;
- Minimum Age: 18 full years;
- Official Documentation: Valid South African ID document (South African ID) or permanent residence;
- Proof of Income: Recent payslip or bank statements from the last 3 months proving regular deposits;
- Proof of Residence: Issued within the last 90 days;
- Active Bank Account: Mandatory for monthly statement direct debit.
Unlike the debit card, issued in 5 minutes at biometric kiosks, the credit card underwent risk analysis at RCS back-office. After that, it was sent by express delivery service (courier) directly to the cardholder’s home.
Is TymeBank Credit Card Better Than Other Options? See the Comparison
To understand the card’s weight in the market, see how it positioned itself against entry-level options from key South African competitors:
| Card | Minimum Income | Monthly Fee | International Fee |
| TymeBank Credit Card | R3 000 | R40.00 | 2.00% |
| Capitec Global One | R5 000 | R45.00 to R51.50 | R1 to R3 fixed |
| Absa Flexi Core | R2 000 | R44.00 | 2.75% |
| Standard Bank Blue | R5 000 | R40.00 | 2.75% |
| African Bank Black | R3 000 | R50.00 | 2.00% |
TymeBank stood out by eliminating micro-fees that erode the balance of lower-income consumers.
However, the R50 000 cap and the absence of travel insurance limited its acceptance, mainly among higher purchasing power brackets.
All Benefits of the TymeBank Credit Card
The product was specifically designed to democratize access to plastic money in South Africa. Below, check out in detail each of the advantages that highlighted the card in the market:
1. Accessible Minimum Income Requirement of R3,000
The main entry barrier in major South African banks has always been high salary requirements. Institutions like Standard Bank and Capitec required R4,000 or R5,000 or more.
TymeBank lowered this bar to just R3,000 per month.
This measure opened the doors of formal credit to middle- and low-income workers who were previously restricted to expensive informal loan lines.
2. Up to 55 Days Without Interest Charges
The cardholder had a grace period of up to 55 days interest-free to settle purchases made in physical and digital retail stores.
It is worth noting that the benefit applied to point-of-sale terminal transactions paid in full by the statement due date.
This flexibility allowed customers to organize household cash flow without additional costs.
3. Multiplied Points on Pick n Pay Smart Shopper
Integration with the Smart Shopper program of the Pick n Pay supermarket chain represented the biggest daily consumption attraction.
Moreover, the card allowed earning points on all global purchases processed by the Visa network.
In addition, purchases made directly at Pick n Pay stores earned up to four times more points, lowering essential food and grocery expenses.
4. Completely Free SMS Transaction Alerts
Traditional banks in South Africa charge monthly fees or individual costs for each transaction notification via SMS. In contrast, TymeBank set this fee at zero.
The cardholder received real-time updates on suspicious movements and purchase confirmations without paying anything extra at month-end.
5. Competitive International Exchange Fee of 2%
For those purchasing on foreign websites or traveling internationally, the card applied a fixed currency exchange commission of 2.00% on the transaction value.
This rate was well below the average of 2.75% charged by most competing institutions in the country, resulting in direct savings on foreign currency expenses.
Frequently Asked Questions (FAQ)
- Does TymeBank still issue credit cards in South Africa? New applications for the traditional credit card in partnership with RCS have been suspended. For installment purchases, the bank prioritizes the MoreTyme (BNPL) service. It also offers structured personal loan lines.
- What was the maximum limit for the TymeBank Credit Card? The maximum limit granted was R50 000, subject to credit score analysis and proof of income from the cardholder.
- How do installments work on MoreTyme? The customer pays the first installment at the time of purchase. Then, they split the remainder into two installments (at 30 and 60 days) with zero interest, provided payments are made on agreed dates.
- How to pay a remaining balance on the TymeBank RCS card? Customers who still have an outstanding balance continue managing settlement through official RCS channels or via direct debit agreed upon in the credit contract.
Conclusion
The TymeBank credit card in South Africa exemplifies how entry barriers in traditional revolving credit require operational maturity and channel alignment.
The card left important lessons about reliance on external partners. Despite this, the institution consolidated a consistent transition to GoTyme Bank. It replaced maintenance fees with interest-free installment mechanisms and regulated personal loans.
Not sure if you want this card? See the Tenpo Mastercard card benefits now. This is a direct competitor to TymeBank. In some aspects, it is even better.